Building Enduring Essential Services Businesses
TurnKey is an operator-led independent sponsor pursuing a buy-and-build strategy across fragmented, non-discretionary essential services markets.
We identify strong founder-led businesses, acquire the right initial platform, install institutional operating infrastructure, and pursue disciplined organic growth and strategic add-on acquisitions. TurnKey combines entrepreneurial speed with institutional underwriting discipline.
Atlanta, Georgia · Independent Sponsor · Operator-Led
One Platform. Multiple Paths to Compound Value.
TurnKey's strategy is to acquire durable essential-services companies operating in fragmented markets where professionalization, technology, systems, strategic M&A, and improved capital access can materially increase enterprise value.
TurnKey is not building a passive portfolio. We intend to actively operate alongside management teams and build scalable platforms capable of executing subsequent acquisitions.
Essential Demand
Prioritize non-discretionary or mission-critical services where customers cannot simply defer the work indefinitely.
Fragmented Markets
Target industries with large numbers of independent operators and meaningful opportunities for consolidation.
Operational Upside
Seek businesses where technology, automation, sales infrastructure, financial controls, talent, and centralized services can improve performance.
Buy + Build
Use the initial acquisition as a platform for organic growth and disciplined tuck-in acquisitions.
A Disciplined Acquisition Box
What We Avoid
Four and a Half Months. One $80M Transaction. A Better Investment Process.
TurnKey recently spent approximately four and a half months pursuing and diligencing an approximately $80 million enterprise-value transaction. We ultimately chose to walk away.
That decision reinforced an important principle:
The objective isn't to close a deal. The objective is to close the right deal.
The process created meaningful institutional knowledge before TurnKey's first acquisition and materially sharpened our underwriting criteria, diligence process, capital relationships, and approach to transaction execution.
What We Took Forward
Cash Conversion Matters
Reported EBITDA means significantly less when working capital and receivables cannot support it.
Quality of Earnings Matters
Accounting quality and financial transparency must support institutional underwriting.
Structure Matters
Legal entities, contracts, customer relationships, financing arrangements, and liabilities must be understood before capital is committed.
Alignment Matters
Seller incentives, management incentives, capital partners, lenders, and TurnKey must ultimately be pulling in the same direction.
Walking Away Is Part of the Job
Months invested in diligence do not justify deploying capital into the wrong transaction.
We would rather wait for a fat pitch than manufacture conviction around an average deal.
Founder-Led. Full-Time.
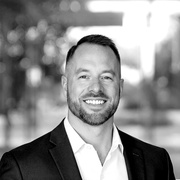
Ryan Lamothe
Founder & Operator
Atlanta, Georgia
Dedicated full-time to TurnKey. Leads acquisition sourcing, underwriting coordination, seller negotiations, capital formation, lender relationships, marketing, systems, automation, and transaction execution.
Personally responsible for
The model intentionally keeps TurnKey lean during the search period. Rather than building a large pre-acquisition payroll, Ryan performs many functions that would otherwise require multiple employees or outside service providers while leveraging experienced advisors, legal counsel, lenders, investors, and transaction specialists where appropriate.
Ryan previously built and exited ShopHawk and has spent the current search developing direct experience across sourcing, diligence, capital formation, lender negotiations, transaction structuring, and operating-system development.
Built With Experienced Operators Around the Table
Brad McIntosh
M&A / Operating Advisor · 0.50% TurnKey Equity
Current Vice President and Head of M&A at an approximately $45 million revenue towing organization. Former business partner of Ryan in ShopHawk. Brings direct operating, acquisition, and transaction experience.
Jonathan Wilcox
Investor & Advisor · 5.0% TurnKey Equity
Early Investor — $125K invested at $2.5M post-money during TurnKey's formation
Former Chief Investment Officer of an insurance company. Current owner-operator of a mobile heavy-duty diesel mechanic business in Oklahoma City. Brings experience across capital allocation, institutional investing, entrepreneurship, and operating businesses.
Marc Noland
Finance & M&A Advisor
Atlanta-based owner of two operating companies. Former CFO of a business that has subsequently grown to approximately $900 million in revenue. Brings CFO-level financial leadership, operating experience, and M&A perspective.
Kevin Casenhiser
Legal & Strategic Advisor · 0.25% TurnKey Equity
Former General Counsel at ATI, with approximately 15 years at the organization. Brings extensive legal, transaction, governance, and operating-company experience.
Equity percentages reflect TurnKey HoldCo equity and do not represent a current valuation.
Institutional Infrastructure Without Institutional Overhead
TurnKey has assembled the professional relationships required to evaluate and execute sophisticated lower-middle-market transactions.
Legal Counsel
Polsinelli — a nationally recognized Am Law 100 firm.
Debt Capital
Relationships across banks, private credit, and strategic credit providers.
Equity Capital
Relationships with family offices, private investment firms, independent sponsor capital providers, and experienced operator-investors.
Transaction Support
Access to accounting, Quality of Earnings, diligence, insurance, and other specialized transaction resources as required.
TurnKey is currently working toward a potential Investment Capacity Agreement (ICA) with an institutional equity partner. An ICA could provide predefined acquisition capacity and allow TurnKey to pursue qualifying transactions more aggressively. This arrangement is being evaluated and is not currently committed unless and until definitive documentation is in place.
Predefined investment capacity for qualifying transactions.
Source → Underwrite → LOI → Assemble Capital → Close → Operate
Neither structure changes the fundamental objective: maintain discipline and deploy capital only when the underlying opportunity warrants it.
$500K–$1.0M Search Capital
12 months of dedicated runway to source, diligence, negotiate and capitalize the first platform acquisition.
Capital Sought
$500K–$1M
$500,000–$1,000,000
Target outcome: First platform under LOI within six months, with sufficient capitalization to remain disciplined if the right transaction takes longer.
The purpose of capitalization is not to create pressure to transact. It is to create enough runway to remain selective and move aggressively when the right opportunity appears.
Illustrative Use of Search Capital
Two illustrative scenarios showing the expected allocation of search capital across the funded search period. The budget represents an expected allocation rather than rigid spending commitments.
Illustrative only. Actual allocation will vary based on transaction activity, timing, and capital structure.
Transaction Expense Recovery
Certain transaction-specific costs associated with a successful acquisition may be included in the acquisition's Sources & Uses and reimbursed to TurnKey at closing, subject to lender approval, equity partner approval, definitive transaction documentation, and the specific capital structure.
Recovered capital may then strengthen post-close liquidity, support the acquired platform, fund subsequent acquisition activity, or remain available for other approved corporate purposes.
For planning purposes, TurnKey generally intends to maintain a disciplined ceiling of approximately $250,000 in transaction-specific expenses for a traditional transaction unless deal size or complexity justifies otherwise.
Founder compensation, ordinary operating expenses, and general search overhead are not automatically reimbursable transaction expenses.
A Disciplined Path to the First Platform
Build the Pipeline
- Aggressive proprietary sourcing
- Intermediary relationships
- Industry mapping
- Seller meetings
- Capital partner alignment
- Target screening
Find the Platform
- Management meetings
- Preliminary underwriting
- Site visits
- Capital structure modeling
- Indications of Interest
- Target: First platform under LOI
Diligence + Capitalize
- Quality of Earnings
- Legal diligence
- Commercial diligence
- Debt financing
- Equity syndication
- Management planning
Close + Build
- Close initial platform
- Implement operating cadence
- Deploy systems and reporting
- Identify initial tuck-ins
- Launch organic growth initiatives
- Begin next acquisition pipeline
This timeline represents execution targets, not a commitment to close an acquisition simply to meet a deadline. Investment discipline takes priority over schedule.
Two Paths to Partnership
TurnKey is open to structuring the search capitalization around the investor's strategic value and objectives.
Search Capital / Debt
Designed primarily for capital providers seeking a defined financial return rather than long-term strategic participation.
Indicative economics
1.5× invested capital payable upon the closing of the first qualifying platform acquisition.
If the search extends beyond 12 months, the repayment multiple steps up to compensate the investor for additional duration and risk.
Final maturity, step-up economics, qualified transaction definition, repayment mechanics, and other terms would be established in definitive documentation.
Strategic Capital + HoldCo Equity
For investors capable of creating meaningful strategic value beyond their capital, TurnKey is open to discussing a combination of structured search capital and TurnKey HoldCo equity.
Strategic value may include
We do not view every dollar of capital equally.
The right strategic partner can create substantially more enterprise value than a passive source of financing, and TurnKey is willing to structure economics accordingly.
Patience Is an Investment Advantage
Independent sponsors face a structural tension.
The best acquisition strategy requires patience.
An undercapitalized search creates pressure to close.
TurnKey wants the opposite.
Search capital creates the ability to walk away from mediocre opportunities, pursue proprietary situations, invest in proper diligence, negotiate from strength, and move quickly when an exceptional opportunity appears. The recent transaction demonstrated that discipline firsthand.
We spent four and a half months pursuing a transaction — and walked when the facts changed.
Capitalizing the search is designed to preserve that discipline.
Acquire. Professionalize. Compound.
TurnKey's objective is not simply financial engineering. We intend to build better operating companies. That means stronger reporting, disciplined financial controls, modern sales and marketing systems, automation, talent development, management accountability, recurring-revenue expansion, and thoughtful M&A.
The goal is to create businesses that become more valuable because they are fundamentally better companies.
We Only Need One Exceptional Platform to Start.
TurnKey is seeking aligned capital partners who understand that the best independent sponsor returns begin before the acquisition — with disciplined sourcing, patient underwriting, and the willingness to walk away.
TurnKey is not attempting to predict exactly when the right acquisition will appear. It is building the capital, relationships, infrastructure, and discipline required to recognize it and execute when it does.
Reach out directly to Ryan.
TurnKey
Atlanta, Georgia
Operator-Led Independent Sponsor
Essential Services · Buy + Build